 Socio Today
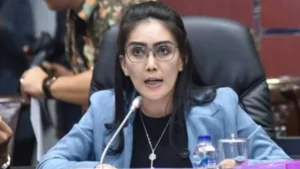
Jakarta – A wave of indignation swept across national legislative circles following a viral social media disclosure by Rieke Diah Pitaloka, a member of Commission VI of the House of Representatives (DPR RI) representing the Indonesian Democratic Party of Struggle (PDI-P). Pitaloka openly expressed her profound anger and frustration after discovering that Pesantren Al-Fath Jalen—an Islamic boarding school in Tambun Utara, Bekasi Regency, founded by the late Kiai Yasin—had been issued persistent and unjustified billing statements for the Land and Building Tax (Pajak Bumi dan Bangunan, or PBB).
The incident, which quickly drew widespread public attention, was documented and shared via Pitaloka’s official Instagram account under the handle @riekediahp through the Viral for Justice segment, underscored by the hashtag #SavePesantrenIndonesia. The emotional outburst captured on video showed the seasoned lawmaker directly calling out Finance Minister Purbaya Yudhi Sadewa, urging immediate intervention from central authorities to halt what she characterized as predatory and legally flawed tax collection practices targeted at non-profit educational and religious institutions.
The controversy highlights a recurring systemic friction point in Indonesia between local tax administration policies and the legal protections afforded to foundational religious and educational infrastructures. As details of the case continue to unfold, lawmakers, local government officials, and legal experts are closely examining the institutional oversights that allowed tax liabilities to accumulate against an exempt entity, prompting broader discussions regarding the enforcement of tax exemptions for public-benefit facilities nationwide.
Chronology of Events and the Genesis of the Tax Dispute
The unfolding situation at Pesantren Al-Fath Jalen is rooted in a history that spans over a decade, marked by administrative ambiguity and shifting local tax enforcement policies. According to testimonies provided by institutional administrators, the foundation’s journey with property documentation began around 2010. During this period, representatives of the pesantren visited the local Office of Religious Affairs (Kantor Urusan Agama, or KUA) to process the official waqf (endowment) certification for the land upon which the boarding school operates.
At the time, institutional representatives were informed by KUA officials that the process of securing a waqf certificate would be both prolonged and financially demanding. Crucially, the administrators were explicitly told by local religious administrative personnel that because the land was dedicated entirely to religious and educational purposes as a registered Islamic boarding school, it was legally exempted from the annual Land and Building Tax (PBB). Operating as laypersons with limited legal and administrative literacy regarding fiscal regulations, the management accepted these assurances in good faith, assuming the institution possessed permanent immunity from property tax assessments.
For more than a decade, this understanding remained unchallenged. However, the operational landscape shifted dramatically in 2024. Without prior warning, formal notification letters regarding outstanding tax arrears began arriving at the pesantren. The situation escalated severely in 2025 when administrators received an official notice warning that the property faced potential administrative seizure, including the installation of police lines due to unfulfilled tax payments.
Naili, a key administrator at Pesantren Al-Fath, recounted the emotional toll this escalation took on the community and its leadership during an interview with Rieke Diah Pitaloka. Naili admitted that the threat of asset seizure caused profound distress, particularly for the institution’s founder, the late Kiai Yasin. The anxiety and stress associated with the impending punitive tax measures reportedly coincided with a sharp decline in the elderly cleric’s health, culminating in his passing shortly after the administrative threats intensified.
Legal Framework Governing PBB Exemptions for Educational and Religious Institutions
The core argument presented by Rieke Diah Pitaloka and supported by local legislators centers on the strict interpretation of existing statutory frameworks governing the imposition of Land and Building Tax in Indonesia. Under national regulations, specifically referencing provisions akin to Article 38 of regional taxation frameworks and prevailing fiscal laws, property tax obligations are explicitly waived for specific categories of public-benefit real estate.
The law dictates that the imposition of PBB does not apply to land and buildings owned or utilized exclusively for public interest purposes across several designated sectors: religious worship, social welfare, public health, national education, and cultural preservation. The fundamental prerequisite for this exemption is that the property must not be operated with the intent of generating commercial profits.
Pesantren Al-Fath Jalen, functioning as a non-profit Islamic boarding school providing traditional education, religious instruction, and community shelter, clearly falls within the statutory definition of an exempt entity. During her visit to the facility, Pitaloka emphasized this legal reality with strict adherence to legislative intent. She argued that institutions like Pesantren Al-Fath effectively shoulder responsibilities that rightfully belong to the state—namely, educating the nation’s youth and providing moral and social infrastructure.
"Yayasan abang gue tuh nggak cari untung. Berani-beraninya nagih. Ya, kita selesaikan secara adat hukum maksudnya," Pitaloka stated firmly during her inspection, highlighting the non-commercial nature of the foundation and signaling that the imposition of taxes on such a facility represents a fundamental miscarriage of administrative justice. She further elaborated that educational boarding institutions act as extensions of public service, making the aggressive pursuit of municipal tax revenue against them both legally indefensible and socially counterproductive.
Direct Appeal to Minister Purbaya Yudhi Sadewa and Municipal Legislative Response
The decision by Pitaloka to broadcast her intervention and directly invoke the name of Finance Minister Purbaya Yudhi Sadewa transformed a localized administrative error into a matter of national legislative scrutiny. By calling out the central financial leadership, the PDI-P lawmaker sought to draw attention to potential systemic disconnects between national tax policies and the operational realities enforced by regional revenue bodies (Badan Pendapatan Daerah, or Bapenda).
"Tiba-tiba ada orang datang dari Badan Pendapatan Daerah nagih pajak. Kang Purbaya, tolong Kang Purbaya," exclaimed Pitaloka in the widely circulated video, urging the Finance Minister to rein in regional tax collectors who issue billing statements without conducting adequate preliminary verifications of property status.
In alignment with national legislative oversight, local representation stepped forward to address the immediate crisis. Nyumarno, a member of the Bekasi Regency Regional House of Representatives (DPRD), was present during the inspection and corroborated the legal protections shielding the institution. Nyumarno confirmed that regional regulations in Bekasi Regency explicitly mandate exemptions from PBB for recognized places of worship and non-commercial educational institutions like pondok pesantren.
However, Nyumarno acknowledged a persistent structural flaw in the execution of regional tax policies: the lack of comprehensive sosialisasi (public outreach and administrative cross-checking) prior to the issuance of mass billing notices. He noted that revenue authorities frequently generate automated or generalized tax demands based purely on geographic data without filtering out properties possessing documented religious or educational exemptions.
"Di Kabupaten Bekasi memang sudah ada aturan bahwa tempat ibadah atau pondok pesantren yang tidak komersial bisa diajukan untuk tidak bayar PBB," explained Nyumarno during the on-site discussion. Addressing the immediate concerns of the pesantren management, Nyumarno committed to providing direct institutional assistance to resolve the dispute, promising to personally oversee the administrative process required to nullify the accumulated tax bills and permanently secure the property’s tax-exempt status.
Broader Implications for Tax Administration and Islamic Boarding Schools Nationwide
The incident involving Pesantren Al-Fath Jalen serves as a microscopic reflection of a broader administrative challenge facing religious and educational foundations across Indonesia. Pondok pesantren, many of which operate on historically endowed lands or informal waqf arrangements finalized decades ago, frequently encounter administrative friction when modern municipal tax collection systems are digitized and expanded by regional governments.
Analysts and legal observers point out that several critical systemic issues contribute to these recurring conflicts:
-
Administrative Fragmentation: A historical disconnect between local religious bureaus (such as the KUA), national land agencies (BPN), and regional tax collection offices (Bapenda) often results in incomplete institutional profiling. When land titles are updated or tax databases are computerized, the exempt status of historical waqf properties is occasionally omitted.
-
Automated Mass Taxation: The increasing reliance on automated tax assessment systems by regional governments to meet local revenue targets (Pendapatan Asli Daerah, or PAD) can lead to indiscriminate billing. Systems optimized for revenue generation frequently fail to cross-reference property identifiers with non-profit exemption registries unless proactively flagged by administrators.
-
Vulnerability of Grassroots Institutions: Many traditional Islamic boarding schools are managed by clerical families or local communities with limited access to professional legal and tax counseling. When faced with aggressive municipal collection tactics or threats of asset seizure—such as the police-line warnings issued in this case—administrators often experience acute distress due to a lack of familiarity with legal dispute mechanisms.
The swift intervention by high-profile figures like Rieke Diah Pitaloka and local legislators successfully prevented immediate punitive action against Pesantren Al-Fath, but experts emphasize that systemic reforms are necessary. To prevent similar incidents from recurring, policymakers have suggested the implementation of automated exemption mapping within regional tax databases, mandatory inter-agency data sharing between religious affairs offices and local tax authorities, and comprehensive administrative amnesties for non-profit educational institutions facing historical tax arrears.
As the Ministry of Finance and regional bodies evaluate the fallout from the Bekasi case, the overarching objective remains the safeguarding of institutions that form the backbone of community education and spiritual development in Indonesia, ensuring they remain free from the burden of inappropriate fiscal taxation.