 Socio Today
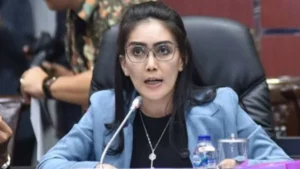
Jakarta — A wave of indignation swept across the Indonesian political landscape following a viral video featuring Rieke Diah Pitaloka, a member of Commission VI of the House of Representatives (DPR RI) from the Indonesian Democratic Party of Struggle (PDI-P). Pitaloka openly expressed her frustration and anger upon discovering that Pesantren Al-Fath Jalen, an Islamic boarding school founded by the late Kiai Yasin in Tambun Utara, Bekasi Regency, West Java, was hit with formal notifications demanding the payment of Land and Building Tax (PBB).
The controversy erupted after Pitaloka uploaded a video to her personal Instagram account (@riekediahp) under the banner of "Viral for Justice" with the accompanying hashtag #SavePesantrenIndonesia. In the recording, which quickly gained traction across various social media platforms, the lawmaker directed her remarks toward Finance Minister Purbaya Yudhi Sadewa, passionately questioning the rationale behind taxing a non-profit educational and religious institution.
This incident has reignited a broader national discourse regarding the administrative oversight, regulatory alignment, and tax enforcement mechanisms targeting religious and educational foundations throughout Indonesia. While tax regulations explicitly grant exemptions to non-profit entities serving the public good, gaps in bureaucratic coordination often leave grassroots institutions vulnerable to aggressive revenue collection efforts by regional bodies.
Chronology of the Dispute at Pesantren Al-Fath
The roots of the conflict trace back to 2010, when the leadership of Pesantren Al-Fath sought to formalize their land status by processing a waqf (endowment) certificate through the local Office of Religious Affairs (KUA). According to Naili, a representative and administrator of the boarding school, the administrative process at the time was both prolonged and financially burdensome for the modest religious institution.
During the proceedings, local KUA officials verbally assured the school administrators that Islamic boarding schools and recognized religious institutions were legally exempt from paying Land and Building Tax. Relying on this guidance, and operating with limited legal and administrative literacy regarding fiscal policies, the foundation’s leadership considered the matter settled for more than a decade.
However, the situation took a drastic turn in 2024 when the pesantren began receiving official tax billing statements from the regional revenue agency. The financial burden compounded quickly, culminating in a severe escalation in 2025. Administrators received formal notices warning that the historical property could face punitive measures, including being cordoned off with police lines, due to the accumulated unpaid taxes.
Naili recounted the profound emotional toll the situation inflicted on the school’s leadership, particularly noting the immense stress experienced by the late Kiai Yasin shortly before his passing. The threat of legal enforcement against a revered community sanctuary devastated the residents and caretakers, who viewed the tax demands as an existential threat to the school’s mission of providing free or affordable education to underprivileged children.
Legislative Framework and Legal Exemptions
During her on-site visit to Pesantren Al-Fath, Rieke Diah Pitaloka sharply criticized the local revenue officers, emphasizing that the actions taken against the institution violated existing statutory protections. Pitaloka explicitly cited Article 38 of the prevailing regulations governing the Land and Building Tax, which dictates that tax objects used exclusively for public interest—specifically within the realms of religion, social welfare, health, national education, and culture—are entirely exempt from PBB liabilities, provided they do not operate with a commercial profit-seeking motive.
Pitaloka argued that religious boarding schools essentially fulfill obligations that naturally fall under the purview of the state, such as educating marginalized youth and instilling moral and social values. By bearing these responsibilities, institutions like Pesantren Al-Fath alleviate the government’s burden in providing comprehensive public education.
Echoing these legal arguments, Bekasi Regency Regional House of Representatives (DPRD) member Nyumarno, who accompanied Pitaloka during the visit, confirmed that local regional regulations (Perda) explicitly outline tax exemptions for non-commercial places of worship and educational facilities.
Nyumarno acknowledged that while the legal framework exists to protect such entities, systemic flaws in bureaucratic execution often lead to administrative errors. He noted that tax bills are frequently dispatched without adequate cross-agency coordination or prior socialisation with local communities, catching vulnerable institutions off guard. To rectify the situation at Pesantren Al-Fath, Nyumarno pledged to provide direct legislative and administrative assistance to ensure the complete annulment of the tax liabilities.
Broader Implications for Religious and Educational Institutions in Indonesia
The public outcry led by Pitaloka highlights a recurring systemic vulnerability faced by traditional religious and educational institutions across the archipelago. Many pesantren, particularly those situated in rural or semi-urban areas, operate on informal or semi-formal administrative foundations established decades ago. These institutions frequently struggle to navigate the modern, digitized, and centralized tax administration systems implemented by regional governments seeking to maximize local revenue generation (Pendapatan Asli Daerah – PAD).
Experts in public policy and tax law have pointed out several core systemic issues underlying incidents of this nature:
- Bureaucratic Disconnect: A chronic lack of synchronization between central ministries (such as the Ministry of Religious Affairs and the Ministry of Finance) and regional revenue agencies (Badan Pendapatan Daerah – Bapenda) often results in outdated land registries and failure to cross-reference exempt properties.
- Asymmetrical Access to Information: Grassroots educational foundations often lack dedicated legal or accounting departments, making it difficult for them to navigate complex exemption application procedures or contest erroneous tax assessments.
- Aggressive Regional Revenue Targets: Under pressure to boost local financial independence, municipal and regency governments sometimes implement aggressive tax collection drives without conducting thorough verification of the socio-economic status and legal classifications of targeted properties.
The viral exposure of the Pesantren Al-Fath case has prompted calls from civil society organizations for the Directorate General of Taxes and regional authorities to institute a nationwide audit and moratorium on tax collections directed at recognized religious and educational foundations. Activists argue that safeguarding historical institutions of learning is paramount to preserving Indonesia’s cultural and religious heritage, warning that heavy-handed fiscal policies threaten the survival of community-based education.
As political pressure mounts on national figures such as Finance Minister Purbaya Yudhi Sadewa and regional administrators in Bekasi, the resolution of the Pesantren Al-Fath case is expected to serve as a critical precedent. Observers will be closely monitoring whether executive authorities implement structural safeguards to prevent similar administrative oversights from threatening non-profit educational sanctuaries in the future.