Jakarta — In a significant pivot for its long-term global operations, Japanese automaker Mitsubishi Motors is recalibrating its core geographic priorities. Facing intense market disruption from aggressive Chinese electric vehicle (EV) manufacturers entering Southeast Asia and experiencing a sharp contraction in key markets like Thailand, the company is deliberately stepping back from its decades-long heavy reliance on the Association of Southeast Asian Nations (ASEAN) region.
This strategic recalibration marks a defining moment for the manufacturer, which historically pioneered early industrial investments in Southeast Asia during the mid-20th century. By realigning its product pipeline toward advanced markets such as North America, Japan, Australia, and New Zealand, Mitsubishi aims to secure sustainable profitability, even as industry analysts warn of potential risks stemming from a diminished operational scale in its former stronghold.
The Awakening: Overreliance on ASEAN and the Chinese EV Disruption
For decades, Southeast Asia functioned as Mitsubishi Motors’ most reliable engine for global volume and profitability. The automaker established its footprint early, commencing vehicle production in Thailand as far back as 1966 before systematically expanding manufacturing and distribution networks into Indonesia, the Philippines, Vietnam, and Malaysia. Over the past decade, this foundational commitment bore fruit on paper: the ASEAN region’s contribution to Mitsubishi’s total global sales swelled significantly, climbing from approximately 20 percent to 31 percent.
However, the automotive landscape in Southeast Asia has undergone a profound transformation. The rapid proliferation of Chinese automotive brands—backed by state subsidies, aggressive pricing strategies, and an advanced ecosystem of affordable electric vehicles—has fundamentally disrupted legacy market share dynamics. Thailand, historically one of Mitsubishi’s most lucrative export hubs and domestic sales powerhouses, has seen the Japanese manufacturer’s sales plummet by roughly half over the past five years.
Simultaneously, even in markets where Mitsubishi has maintained a relative stronghold, signs of fatigue are emerging. In the Philippines, where sales performance has historically remained robust, volume growth has slowed noticeably since the beginning of fiscal year 2026 in April.
These mounting pressures culminated in a candid admission by Mitsubishi Motors Chief Executive Officer Takao Kato. During a comprehensive briefing outlining the company’s medium- and long-term business vision held in late May, Kato acknowledged the vulnerability of the company’s regional concentration.
"We were overly skewed toward products tailored for the ASEAN market under our previous medium-term business plans," Kato stated, according to reports from Nikkei Asia. This over-dependency left the company ill-prepared to counter the swift market capture by Chinese manufacturers who flooded the region with competitively priced New Energy Vehicles (NEVs) starting around 2020—a segment where Mitsubishi has been conspicuously slow to introduce localized commercial offerings.
A Dramatic Pivot in the Product Pipeline
The recognition of these structural headwinds has translated into a drastic overhaul of Mitsubishi’s global product roadmap. Under its newly formulated mid-term strategy leading up to fiscal year 2031, the company plans to introduce a total of 13 new vehicle models over a six-year period.
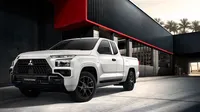
Crucially, the allocation of these upcoming models reveals a stark downgrade in Southeast Asia’s priority status. Out of the 13 planned vehicle launches globally, only one model has been designated specifically for the ASEAN market: a generational redesign of the immensely popular Xpander multi-purpose vehicle (MPV), the original version of which was first launched in 2017.
This represents a severe contraction in regional product investment compared to previous business cycles. Under its preceding medium-term plan covering fiscal years 2023 through 2025, Mitsubishi had originally scheduled four distinct new model introductions tailored exclusively for the Southeast Asian market.
By contrast, approximately 10 new models in the current pipeline are being redirected toward advanced economies. This includes a heavy focus on minicars (kei cars) and next-generation battery electric vehicles (BEVs). Furthermore, to accelerate its footprint in mature markets without absorbing prohibitive internal research and development costs, Mitsubishi is increasingly leveraging Original Equipment Manufacturer (OEM) partnerships. A primary example of this strategy is the rollout of a compact electric vehicle assembled by Taiwan’s Foxconn, slated for introduction in Australia and New Zealand.
Financial Targets and Scalability Concerns
The strategic relocation toward advanced markets is accompanied by tempered financial and volume expectations. Mitsubishi Motors has established a global sales target of 900,000 units for the fiscal year ending in March 2030. While this represents a modest 13 percent increase compared to the projected figures for fiscal year 2025, it remains drastically lower than the company’s historic peak of 1.24 million units achieved in fiscal year 2018. It is also well below the 1.1 million unit target that the automaker had aspired to under its previous mid-term management framework.
Industry analysts and institutional observers have raised concerns regarding the viability of this new trajectory. Shifting focus away from high-volume emerging markets toward mature economies risks shrinking Mitsubishi’s overall operating scale. In the United States and Japan—the primary pillars of the newly prioritized advanced market strategy—Mitsubishi currently commands a modest market share of only a few percentage points. Moreover, its retail dealership network in these territories is significantly smaller and less resilient than those of major global competitors, having been systematically trimmed down during consecutive years of weak financial performance dating back to the early 2000s.
A Watershed Moment in Corporate Governance
Compounding these operational adjustments are significant structural shifts within the company’s ownership ecosystem. A pivotal tenet of corporate alignment—a multi-party shareholder agreement involving primary stakeholders Nissan Motor Co. and Mitsubishi Corporation—officially expired on October 20.
This agreement was originally forged in the wake of Nissan’s strategic equity investment in Mitsubishi Motors in 2016, a deal that rescued the automaker from a fuel-economy testing scandal. The pact had legally restricted core stakeholders from liquidating their equity stakes in Mitsubishi Motors for a period of 10 years. With this restriction now lapsed, major institutional shareholders are legally empowered to divest or reduce their equity holdings, provided certain procedural conditions—including formal notification or consent from Mitsubishi Motors—are met.
Market sentiment surrounding the expiration has been lukewarm, underscored by lingering bearishness. Share prices for Mitsubishi Motors have experienced a steep decline, trading more than 30 percent below their closing levels on October 20, 2016. Despite the lifting of transfer restrictions, none of the major institutional stakeholders have immediately signaled an intent to divest their holdings. However, the legal decoupling has sparked internal discussions regarding corporate independence.
"As criticism surrounding traditional cross-shareholdings continues to mount globally, corporations must eventually stand entirely on their own merits," noted a representative for a major institutional shareholder within the broader Mitsubishi corporate group.
Implications and the Road Ahead
The strategic recalibration by Mitsubishi Motors serves as a microcosm of the wider disruption facing legacy automakers worldwide. As Chinese electric vehicle manufacturers continue their aggressive outward expansion into traditional Japanese strongholds across Southeast Asia, legacy brands are forced to choose between engaging in margin-eroding price wars in emerging economies or retreating to specialized niches in developed markets.
For Mitsubishi, the decision to pivot toward advanced economies preserves profit margins per unit but exposes the company to fierce competition against global giants with vastly superior EV production capacities. Meanwhile, ceding ground in ASEAN—a region projected to remain one of the world’s primary demographic and economic growth engines over the coming decades—carries long-term strategic risks.
As the company navigates its transition toward a leaner, more technologically modernized product lineup culminating in 2031, its ability to successfully commercialize EVs through strategic partnerships while defending its legacy brand equity in Southeast Asia will determine its viability as an independent global competitor.