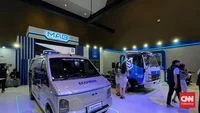
The electric vehicle (EV) manufacturing sector in Indonesia is poised to achieve a significant regulatory milestone, with government leadership expressing high confidence that local production standards will meet rigorous domestic content benchmarks ahead of the decade’s close. Ministry of Industry officials have underscored that the acceleration of domestic manufacturing capabilities, paired with structural commitments to technological transfer, places the country on a firm trajectory to fulfill ambitious industrial localization targets.
Speaking in Jakarta, Minister of Industry Muhammad Sarmuji articulated a strong sense of assurance regarding the readiness of local automotive ecosystems to comply with the mandated 60 percent minimum threshold for Domestic Component Level, commonly known as Tingkat Komponen Dalam Negeri (TKDN), by the year 2027. This regulatory push forms the bedrock of Indonesia’s broader strategy to transform its archipelago into a strategic regional hub for sustainable mobility and advanced green manufacturing.
"I am confident that the industry is ready. The essence of TKDN is local production. If the industry manufactures goods directly within Indonesia, there will certainly be no problem," Sarmuji stated during a press briefing. He further emphasized that ongoing commitments from global and domestic stakeholders regarding technology transfer are actively reinforcing the manufacturing sector’s foundational preparedness.
The Regulatory Roadmap: A Gradual Elevation of Standards
Indonesia’s policy framework for electric vehicle development is underpinned by a meticulously structured roadmap designed to encourage sustainable industrial scaling without imposing immediate, insurmountable compliance burdens on nascent market players. The regulatory architecture scales up domestic value-addition requirements progressively across distinct operational phases.
Under the current regulatory guidelines set by the Ministry of Industry, the transition timeline is mapped out across four key temporal milestones:
- Phase 1 (Foundational Period – Up to 2024): Initial compliance thresholds were established to allow manufacturers time to build local assembly lines, secure component suppliers, and initiate workforce training programs, with baseline TKDN targets set flexibly to accommodate early market entry.
- Phase 2 (Current Implementation – 2025): The mandatory TKDN minimum value is officially pegged at 40 percent for electric two-wheelers and four-wheelers, requiring manufacturers to source a substantial portion of their foundational components—such as chassis, wiring harnesses, and certain interior elements—from domestic suppliers.
- Phase 3 (Medium-Term Escalation – 2027 to 2029): The threshold experiences a decisive upward shift to 60 percent. This phase is anticipated to capture critical high-value components, including battery pack assembly, power control units, and electric drivetrain integration, all executed within domestic borders.
- Phase 4 (Long-Term Maturity – 2030 and Beyond): The final targeted peak mandates an 80 percent TKDN level. By this juncture, the government anticipates a fully integrated domestic electric vehicle supply chain, stretching from raw material processing—such as nickel and cobalt refining—to advanced battery cell manufacturing and vehicle recycling ecosystems.
Industry analysts note that this graduated timeline offers a pragmatic cushion for automotive firms transitioning from pure importation and simple Completely Knocked Down (CKD) assembly to genuinely localized manufacturing models that incorporate comprehensive domestic research, development, and supply chain integration.
Government Oversight and Proactive Industry Engagement
To ensure that the ambitious 2027 target is met without compromising vehicle quality or market affordability, the Ministry of Industry has committed to maintaining rigorous administrative supervision. The state intends to couple aggressive promotional campaigns for domestically manufactured green products with strict compliance auditing.
"Therefore, there is no need to worry; we will always push to prioritize domestic products. We will certainly control the TKDN compliance," Sarmuji affirmed.
This oversight mechanism involves auditing supply chain nodes, verifying raw material origins, and certifying component manufacturers to prevent superficial compliance practices. By enforcing transparency, the government seeks to foster a robust ecosystem where local Tier-1, Tier-2, and Tier-3 automotive component suppliers can thrive alongside established original equipment manufacturers (OEMs).
Furthermore, the emphasis on technology transfer ensures that Indonesian engineers, technicians, and factory operators acquire the specialized competencies required for next-generation automotive production. This human capital development is viewed by economic strategists as critical for sustaining the industry long after initial foreign direct investments have matured.
Navigating Macroeconomic Headwinds: The Impact of Rupiah Fluctuations
Beyond the micro-level regulatory milestones of the electric vehicle sector, broader macroeconomic pressures continue to shape the strategic calculus of Indonesia’s wider manufacturing landscape. In his remarks, Minister Sarmuji addressed the ongoing volatility of the national currency, noting that the persistent depreciation of the Indonesian rupiah against the United States dollar introduces complex operational dynamics for industrial players.
The foreign exchange fluctuations exert a dual, polarized impact on national manufacturers, with the net outcome heavily dependent on an enterprise’s structural orientation regarding supply chain sourcing and product destination markets.
For export-oriented manufacturing firms, a stronger U.S. dollar frequently translates into enhanced revenue margins. When foreign sales denominated in hard currencies are converted back into rupiah, companies operating primarily in international markets realize financial gains that can offset domestic cost pressures. These exporters utilize the windfall to strengthen corporate balance sheets or reinvest in operational efficiency upgrades.
Conversely, manufacturing enterprises that rely heavily on imported raw materials, specialized components, or specialized capital machinery find themselves under immediate margin compression. The rising cost of importing essential production inputs—such as semiconductor chips, specialized chemical compounds, and refined alloy metals—drives up production overheads. If these cost increases cannot be fully passed on to final consumers without destroying market demand, profitability diminishes significantly.
Strategic Mitigation and Adaptation for Industrial Resilience
In light of these persistent currency fluctuations, the Ministry of Industry has strongly urged manufacturing executives to adopt proactive risk management and adaptive operational strategies. The unpredictable nature of global foreign exchange markets necessitates a forward-looking approach to corporate planning.
Sarmuji emphasized that companies must institutionalize robust mitigation frameworks to insulate their operations from external macroeconomic shocks. This includes diversifying supplier bases to incorporate reliable domestic alternatives, utilizing financial hedging instruments to lock in favorable exchange rates, and enhancing forecasting precision to align inventory levels with actual market demand.
"So there must be mitigation for the industry. The industry must also conduct predictions and make self-adjustments," Sarmuji concluded, signaling that government support will be accompanied by an expectation of corporate self-reliance and strategic agility.
Implications for Indonesia’s Green Transition and Economic Future
The alignment of stringent domestic content regulations with adaptive industrial management highlights Indonesia’s determination to steer its economic destiny through a period of profound global transformation. As the global automotive industry races toward electrification, countries that successfully anchor both the demand and supply sides of the EV value chain stand to capture outsized economic benefits.
By insisting on a 60 percent TKDN threshold by 2027, Indonesia is signaling to global automotive giants that access to its rapidly expanding domestic consumer market is contingent upon deep, substantive investments in local industrial capabilities. This approach is expected to attract billions of dollars in foreign investments—particularly in battery manufacturing, charging infrastructure, and vehicle assembly—while simultaneously creating hundreds of thousands of high-skilled jobs for the domestic workforce.
At the same time, the resilience demonstrated by the manufacturing sector in absorbing currency shocks suggests that Indonesia’s industrial base is maturing in sophistication. As regulatory enforcement tightens and macroeconomic strategies adapt to global volatility, the nation’s electric vehicle sector remains firmly on course to establish itself as a formidable pillar of sustainable economic growth in Southeast Asia.