Apple Inc. is steadily advancing its multi-year strategy to transition its tablet lineup from traditional Liquid Crystal Displays (LCD) to advanced Organic Light-Emitting Diode (OLED) technology. According to recent supply chain reports originating from industry insiders, South Korean tech giant Samsung Display is currently positioned to secure the lion’s share of OLED panel orders for the next-generation iPad Air, which is broadly anticipated to make its commercial debut in the first half of 2027.
The impending hardware refresh highlights Apple’s ongoing commitment to standardizing superior visual fidelity, enhanced contrast ratios, and deeper black levels across its diverse portfolio of mobile computing devices. While Apple has maintained its customary corporate silence regarding unannounced hardware roadmaps, extensive leaks from component manufacturers and semiconductor analysts provide a comprehensive glimpse into the strategic maneuvers shaping the consumer electronics supply chain for the late 2020s.
Production Projections and Form Factors for the 2027 iPad Air
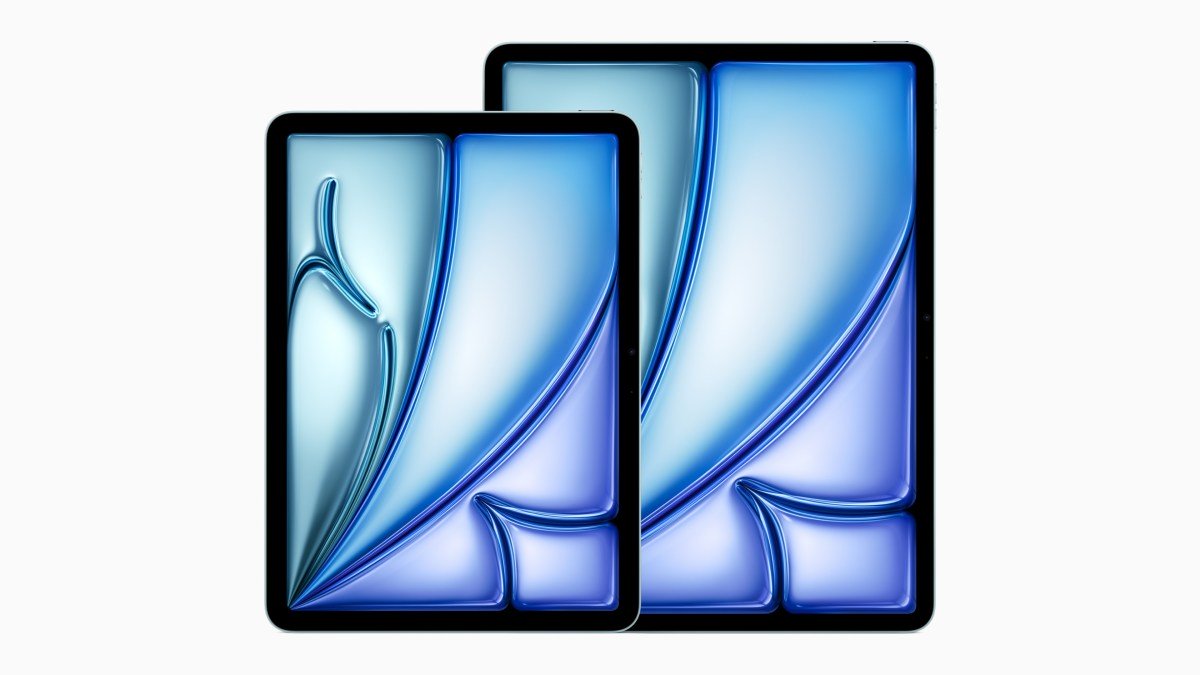
Industry intelligence indicates that Apple is preparing two distinct screen sizes for the upcoming OLED iPad Air generation: an 11-inch model and a larger 13-inch variant. Market analysts project that the cumulative demand for panels dedicated to this specific device lineup will reach between 4 million and 5 million units throughout the course of 2027.
Samsung Display is anticipated to shoulder the vast majority of this substantial manufacturing volume, reinforcing its status as an indispensable partner in Apple’s display ecosystem. However, the South Korean panel maker may not hold an absolute monopoly on the supply chain. Chinese display manufacturing titan BOE Technology Group is aggressively maneuvering to capture a slice of the lucrative contract.
Reports indicate that BOE is actively pursuing orders to supply panels for at least one of the two planned iPad Air sizes. Despite its technological ambitions and massive production capacities centered in facilities like the B12 plant in Chongqing—which houses advanced Generation 6 OLED lines—BOE still faces stringent hurdle rates. The company must successfully navigate Apple’s rigorous quality assurance and panel evaluation protocols before securing commercial mass-production approval. Should BOE clear these technical hurdles, it is expected to serve as a secondary, supplementary supplier, contributing a smaller initial volume compared to Samsung Display.
Comprehensive Landscape of Apple’s 2027 Tablet Display Supply Chain
The strategic allocation of display orders for 2027 underscores a broader tripartite vendor ecosystem involving Samsung Display, LG Display, and potentially BOE. Beyond the iPad Air projections, Samsung Display is concurrently forecasted to handle an equivalent volume of 4 million to 5 million OLED panels for the forthcoming iterations of the compact iPad mini.
Meanwhile, the ultra-premium iPad Pro segment is projected to command a demand of 3 million to 4 million specialized panels. For the flagship Pro models, LG Display and Samsung Display are expected to share the heavier, more complex manufacturing burdens. This distribution illustrates the continued dominance of South Korean display innovators in meeting Apple’s stringent tolerances for high-end mobile screens.
The incorporation of BOE into the iPad Air supply chain, if finalized, would diversify Apple’s sourcing risks and potentially foster competitive pricing dynamics among panel vendors. Nevertheless, historical precedent demonstrates that Apple’s strict quality control mechanisms frequently lead to timeline adjustments or adjusted volume allocations if suppliers experience yield challenges during pre-production phases.
Technological Differentiation: Single-Stack OLED Versus Tandem OLED
A critical element emerging from the 2027 supply chain data involves the deliberate technological segmentation between Apple’s device tiers. While the high-end iPad Pro models leverage cutting-edge Tandem OLED architectures combined with Low-Temperature Polycrystalline Oxide (LTPO) backplane technology, the upcoming iPad Air and iPad mini are expected to employ a more cost-effective configuration.
Industry disclosures suggest that the 2027 iPad Air will utilize a single-stack OLED structure coupled with Low-Temperature Polycrystalline Silicon (LTPS) backplane technology. To fully understand the engineering implications of this design choice, it is necessary to examine the fundamental differences between the two display paradigms:
- Tandem OLED (iPad Pro): Utilizes two stacked emission layers of organic materials. This configuration yields significantly higher peak brightness levels, improved thermal management, extended panel longevity, and enhanced power efficiency under heavy usage loads. Combined with LTPO technology, it allows for variable refresh rates down to 1Hz, optimizing battery consumption.
- Single-Stack OLED (Projected for iPad Air): Employs a single light-emitting layer paired with LTPS transistors. While it lacks the extreme peak brightness and adaptive refresh flexibility of the tandem layout, it still delivers the intrinsic benefits of OLED technology over traditional LCDs—including infinite contrast, pixel-level dimming, vivid color reproduction, and lightning-fast response times—at a substantially reduced manufacturing cost.
This technical distinction allows Apple to maintain clear product differentiation within its catalog. The iPad Pro remains the undisputed flagship for professional creators and power users requiring maximum luminosity and color accuracy, whereas the iPad Air occupies a strategic middle ground, offering premium visual experiences to mainstream and educational users at a more accessible price point.
Evolution of the iPad Air Display: From Liquid Retina LCD to OLED
To contextualize the significance of the 2027 projection, one must examine the current technical baseline of the product family. Apple’s contemporary iPad Air models—such as the iterations introduced in early 2026 featuring advanced processing silicon—rely on Liquid Retina IPS LCD panels equipped with traditional LED backlighting.
The current 11-inch iPad Air standardizes a native resolution of 2,360 by 1,640 pixels, while the 13-inch variant scales up to 2,732 by 2,048 pixels. Both form factors currently support wide color display (P3 gamut), True Tone environmental color adjustment, and seamless compatibility with peripherals such as the Apple Pencil Pro and Apple Pencil USB-C. Certified peak brightness for these LCD screens typically caps out at 500 nits for the smaller model and 600 nits for the larger sibling.
The transition to OLED in 2027 would represent a generational milestone for the middle-tier tablet category. It effectively bridges the technological gap that will have already been crossed by the iPad Pro and iPad mini lines, leaving standard, entry-level base iPads as the primary holdouts utilizing legacy LCD technology.
Market Implications and Broader Industry Impact
The phased migration of Apple’s portfolio toward pervasive OLED adoption carries profound economic consequences for the global display manufacturing sector. As consumer preference definitively shifts away from legacy liquid crystal technologies in premium and mid-tier mobile devices, panel fabricators are forced to reallocate capital expenditures toward advanced emissive production lines.
For Samsung Display, securing the primary contract for both the iPad Air and iPad mini solidifies its revenue streams amidst fierce competition from emerging regional rivals. For Apple, diversifying production risks while maintaining stringent quality gates ensures a resilient supply chain capable of mitigating geopolitical disruptions and component shortages.
As the industry looks ahead to the projected 2027 launch window, market observers will closely monitor BOE’s progress in passing Apple’s rigorous panel qualification audits. Until official announcements are made by Cupertino, these production figures and technical specifications remain subject to refinement based on real-world manufacturing yields, component cost fluctuations, and broader macroeconomic shifts in consumer electronics demand.